
Posted September 17, 2026
By Sean Ring
The Real Fed Chairman
I was wrong.
I told you the Fed would hold. I thought Kevin Warsh would stare down the tape one more time, know his mostly dovish committee had time (two more meetings this year) to hike only 25 basis points (0.25%), and stay his hand.
He didn’t because the doves on his FOMC turned into hawks.
Yesterday, the Fed raised its target rate range by 25 bps to 3.75%-4.00%. The vote was unanimous. This was the first hike since July 2023.
Nine months ago, this same committee was cutting. Its second thoughts have manifested as undoing its previous work.
So let me do what I always do when I’m wrong. Own it, figure out why, and mark my view to market. Because the reason I got this wrong is more useful to you than the call itself.
What Happened
The official story is simple. Inflation won’t be ignored, and it won’t go away.
The CPI ran at 3.4% year over year in August, well above the Fed's 2% target. Core PCE, the Fed's preferred gauge, sat at 3.3%. Remember, the Fed’s “official” (or officially stupid) target inflation rate is 2%. The war with Iran sent oil prices soaring, and those energy costs, especially the blowout in diesel, have been bleeding into everything else for months.
So the Fed hiked. It did so despite the loud, ever-present objections of a President who’s been demanding rates near 1%.
All that’s true, but it’s not why I was wrong.
Why I Missed It
I spent the summer handicapping the Eccles Building. Would Warsh defy the White House? Did the new chairman have the stomach for a hike in an election cycle? Was the consumer too weak?
Those were Fed questions, but the Fed didn’t make this decision.
The bond market did.
Let’s pause to remember former Clinton minion James Carville’s famous quote:
I used to think that if there was reincarnation, I wanted to come back as the President or the Pope or as a .400 baseball hitter. But now I would like to come back as the bond market. You can intimidate everybody.
I had ignored my most important rule: market prices, however flawed and manipulated they are nowadays, are our best source of information.
Check out this chart of the Fed Funds upper bound versus the 2-year yield. Pay special attention to the black arrows.
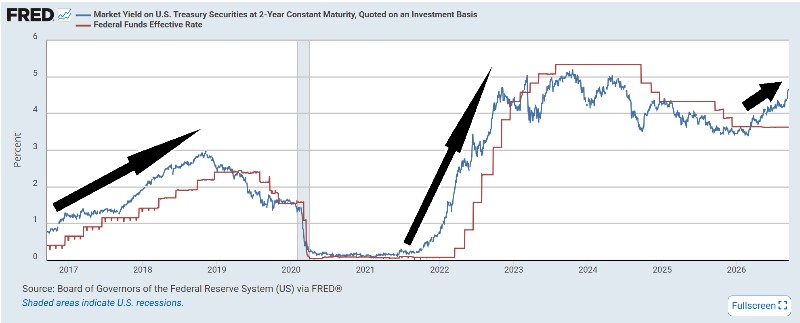
From 2017-2019, the 2y led the Fed. During the 2022 Powell Hikes, same thing. And now, the 2y was in danger of running away from the central bank again. It’s little wonder the vote to hike was unanimous.
In plain English, the market repriced the cost of money months ago. I even titled July’s monthly asset class report, “The Price of Money Just Went Up,” something that must’ve slipped my mind!
Savers, lenders, and foreign creditors all demanded more compensation for holding dollar paper. The Fed’s dictated rate just sat there, further and further from reality, like a stopped clock.
At Jackson Hole in late August, Warsh admitted as much. “Price stability is not self-executing, nor is inflation necessarily mean-reverting,” he said. Hike odds nearly doubled on those words alone. By Wednesday morning, futures markets put the probability at 92%.
But a 92% “probability” is more a verdict than a prediction. The committee just read it aloud.
The Ratification
I should’ve remembered that rather than setting the price of money, the Fed ratifies it.
Remember, prices are the pooled knowledge of millions of buyers and sellers. 500 Fed PhDs may believe the numbers their models spit out, but they can’t convince bond traders those models price credit risk better than they do.
When the Fed's rate drifts too far below the market's rate, one of two things happens. Either the Fed catches up, or the bond vigilantes punish everything priced off it. The chart above makes it clear that the former usually happens. Right now, the Fed is playing catch-up.
Warsh understands whose approval keeps him in business. It's not the President's. The White House can shout all it likes. But only the people who fund a $40 trillion debt can keep Warsh in his seat, something his fellow FOMC voters don’t have to worry about.
A chairman survives by making sure the nation’s creditors are convinced he’s serious. That’s the constituency he pleased on Wednesday.
However, The Donald was easy on the Fed Chairman. From the Wall Street Journal:
President Trump, who picked Warsh after spending months lambasting his predecessor, Jerome Powell, for not cutting rates faster, said Wednesday evening that he was standing by the chairman, who he said has “a very tough board.”
Trump also said he had spoken with Warsh at some point before the meeting. “I talked to Kevin. I said, ‘You might as well vote with the board because it’s not going to matter,’” Trump said. “I said, ‘Do what you want.’”
Afterward, however, the President posted this on his Truth Social account:
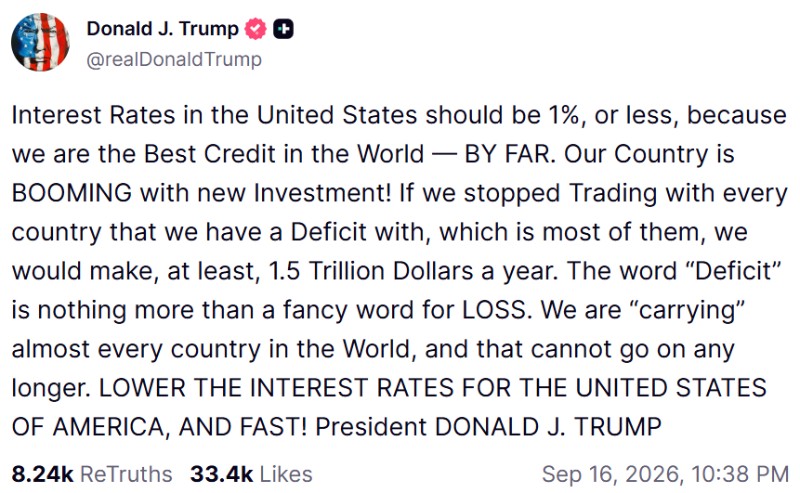
Still, I wouldn’t read this hike as either courage or independence. It’s just the official paperwork on a hike the market implemented weeks ago.
Keep in mind that when the Fed cut through 2024 and 2025, the short end had already priced it. (That’s in the above chart as well, without any arrows.) When the Fed held all this year, the market had boxed it in. Hike, hold, or cut, the committee follows the tape and calls it policy.
What’s Next
Wall Street’s bond traders and analysts now expect more hikes. Several banks have penciled in the next in October and one more in December. Nobody knows yet, including the Fed. Watch the 2-year instead. As it approaches 5%, hiking is likelier to continue, and equities will come under further pressure.
Since 2009, the Fed punished savers and rewarded borrowers. Now cash pays above 4%. The world is tilting back toward the patient, the prudent, and the boring. At least that’s good news.
Keep some of that higher-yielding cash as dry powder. Stack those gold coins and own real assets and businesses with pricing power.
Wrap Up
I got the meeting wrong.
But now I’ll adjust to watching what the awakened bond vigilantes will demand next. Despite the Fed’s move, I don’t see them relenting anytime soon.
Alas, a 25-bp hike doesn’t make a $40 trillion debt disappear.
Have a great day ahead.

The Untied Kingdom
Posted September 16, 2026
By Sean Ring

The Great AI Alibi
Posted September 15, 2026
By Byron King

A Tribute to Washington
Posted September 14, 2026
By Sean Ring

The Bypass Bullseye
Posted September 11, 2026
By Sean Ring
Marked to Market, Marked to Myth
Posted September 10, 2026
By Sean Ring
