Posted September 10, 2026
By Sean Ring
Marked to Market, Marked to Myth
I’ve told this story in recent Rudes, but I’ll recount it quickly, as it’s necessary background for what follows.
In September of 1992, Soros Fund Management bet against the Bank of England (BoE). The UK had pegged the pound to the German mark, and the peg didn't square with economic reality. Soros shorted GBP with everything he could get his hands on.
On September 16th, a day the British still call Black Wednesday, the BoE spent billions defending the peg. It announced two rate hikes in a single day, but neither worked. By nightfall, Britain had quit the peg, and Soros had booked over a billion dollars in profit.
Nice work, if you can get it.
Scott Bessent was working for Soros in his London office then.
Thirty-four Septembers later, Bessent now runs the U.S. Treasury. On Tuesday at Southern Methodist University, he said this about defending the yen and pinning Treasury yields:
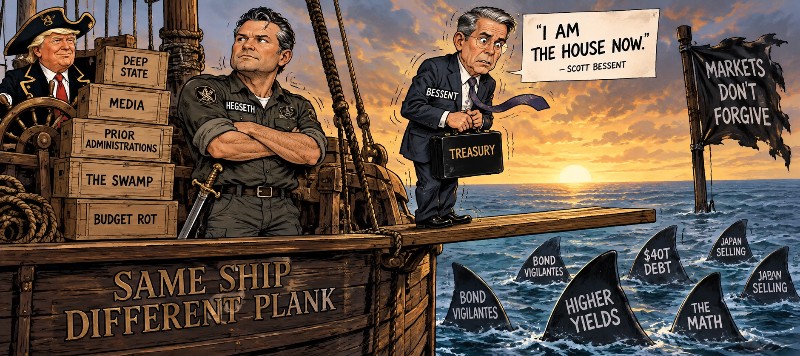
I am the house now. And you can bet against me if you want.
This may have been the dumbest thing he could’ve said. I’ll explain why.
Two Men on the Plank
DC’s favorite game right now is guessing which cabinet secretary walks the plank first. The smart money says Pete Hegseth.
My friend and colleague Emily Clancy laid out that case yesterday in her piece, “Pink Slip Pete.” Under Hegseth, at least 20 generals, admirals, and senior defense officials have been fired or pushed out. Army Secretary Dan Driscoll resigned after warning Trump in person about the upheaval. Senator Thom Tillis, who voted to confirm Hegseth, now wants him gone. And the Senate is sitting on Trump’s pick for Army chief of staff.
It’s a strong case, but I think Scott Bessent gets fired first. Not because he’s necessarily worse at his job, but because of how each man's failures get scored.
Marked to Myth
Hegseth’s organizational failures are real. But they’re arguable.
My friend and colleague Byron King showed why two days ago in the Rude article “The Sea Keeps Honest Books.”
The USS Abraham Lincoln spent 286 days at sea because the Navy operates 291 ships, short of a statutory requirement of 355. That hole took 35 years to dig, through closed shipyards, sold dry docks, and a generation of welders who never got trained. It’s seed corn consumption in battleship gray.
Hegseth inherited that rot. When something breaks on his watch, he can plausibly blame the Deep State, the lamestream media, and three prior administrations. And he’ll be right… mostly.
Hegseth gets marked to myth, rather than to market.
Half the country thinks the Lincoln story is proof of his incompetence. The other half thinks it’s proof The Swamp is fighting back.
Whatever the truth is, leaders don’t keep the officials who perform best. They keep the officials their essential backers insist on. Hegseth is The Base’s man at the Pentagon. Firing him hands a trophy to Tillis and the press corps, and The Donald hates handing out trophies to anyone but The Donald. The President isn’t a villain for keeping him, but a prisoner of that incentive.
Marked to Market
Bessent enjoys no such fog.
We know the Bessent Put. The Treasury doubled its long-end buybacks from $2 billion to at least $4 billion per operation, effective September 9th, running through the November 4th refunding. And yesterday, he raised the announced operation to as much as $6 billion. The market sniffed, then sent yields higher.
Bessent has signaled he will tap the Treasury General Account, a war chest near $950 billion, to fund what he calls the "Treasury Twist." He's also buying yen (by dumping euros, not dollars, much to the chagrin of European finance ministers) so the Bank of Japan won't dump its $1.1 trillion pile of Treasuries (which, it’s rumored, the BoJ is doing anyway).
Against all that firepower stands simple mathematics. The U.S. national debt just passed $40 trillion. The deficit is racing past $2 trillion. The Iran war eats capital daily and isn’t ending anytime soon, no matter what The Donald claims. And pension funds, sovereign wealth funds, insurance companies, and endowments have been on a long-end buyers' strike since late June.
The first buyback announcement rallied bonds for one… whole… day. Then yields drifted right back up. That’s an issue, as the Treasury’s, and hence Bessent’s, credibility is on the line.
Every defended level teaches the shorts where to aim. Bessent knows this better than anyone alive. After all, in 1992 he helped write the playbook, from the other side of the trade.
His problem is that his failure isn't arguable. Stupidly, Bessent made falsifiable statements. There's no Deep State to blame when the long-end yields break out. There are just the market's numbers, Bessent’s threats and actions, and the gaps between them.
Bond positions are marked to market, every minute of every day. The electorate can forgive Hegseth’s myth, but Bessent can't argue with the bond vigilantes.
Warsh's Expiring Option
And now we add the Federal Reserve, because Bessent’s once-and-present colleague, Kevin Warsh, holds the soon-to-be smoking gun.
Warsh has stated he prefers the open market to set rates. That makes the Fed chairman philosophically opposed to the Bessent Put. The funds rate has sat at 3.50% to 3.75% all year, but July's “hold” drew 3 hawkish dissents.
Here's my call: Warsh holds on September 16th, 34 years to the day after Black Wednesday. (For a bit of confirmation bias, my colleague and The Man Himself, Jim Rickards, agrees.) Warsh’s FOMC will hold again on October 28th, just before midterms, so as not to look meddlesome. Then the Fed will hike 25 bps (0.25%) at the December 9th FOMC meeting.
Why December? Because the 2026 FOMC voters are hawkish, and the incoming 2027 FOMC members are dovish, or at least neutral, as far as we know.
The dissenters, Hammack, Logan, and Kashkari, all vote through year-end. In January, they rotate off. In come Goolsbee and Daly, two doves, plus Barkin and a new Atlanta president that The Street expects to lean softer. Miran's board seat expires at the end of January, too.
So December is Warsh's expiring option. He will hike while he still has the votes. Then he’ll let the incoming doves cut through 2027 if the economy demands it. The easing comes from the rotation, not from Warsh caving. That way, he gets his hard-money hike entered into the historical record, looks more like Tall Paul Volcker than Arthur Burns, and then outsources the softening to the new committee.
I offer 1 honest caveat: nobody knows the new Atlanta president's lean yet, and the fights over the Fed's board seats are live wildcards. But that's The Street’s consensus.
Nevertheless, Trump can't fire the Fed chairman he installed. Even if he could, he’d torch his rapidly dwindling credibility. The Treasury Secretary is the movable piece. Warsh pulls the trigger. Bessent takes the bullet.
The Clock
I don’t think Bessent’s peg survives to midterms. Heck, it really isn’t working as I type.
But Trump won’t shoot his general mid-battle. Firing a Treasury Secretary during a bond market defense confirms the defense failed, and that confirmation is a market event in itself. So The Donald will wait. The scapegoat will get served up after November 3rd, but before the new Congress and FOMC take their respective seats in January.
There it is: Bessent goes between the midterms and New Year's. Hegseth is still standing at Easter.
If I'm wrong, you'll read it here first, in plain English, with no excuses.
Wrap Up
When a peg breaks, it never breaks quietly. Keep some of your powder dry for the day the 10-year and 30-year yields get out of control and force sellers dump their holdings.
Remember, Washington whispers are theater. The long bond yield is the vote that counts.
The sea may keep honest books over time. But the bond market marks its books by the minute.
Just Blew It.
Posted October 08, 2026
By Sean Ring
Fission Accomplished?
Posted October 07, 2026
By Sean Ring

The Lease of Their Worries
Posted October 06, 2026
By Sean Ring

You Can’t Print a Smelter
Posted October 05, 2026
By Sean Ring

Pardon My Financial French
Posted October 02, 2026
By Sean Ring