Posted April 17, 2025
We’re Screwed If We Don’t Do the Math
Most economists agree that there’s an inverse relationship between women’s literacy and birth rates.
Economists concluded that the more women read (and are educated), the less they want children.
I’ve always thought that conclusion didn’t match reality. I believe the more women can do the math, the fewer children they want (for lifestyle reasons).
That is, numeracy, rather than literacy, drives decision-making.
There are many examples of career women who can afford – and have – more children. Sara Blakely, Victoria Beckham, and Amy Coney Barrett come to mind.
But this column isn’t about demographics. It’s about innumeracy, which we’ll define as incompetence with numbers. It’s what I think society’s big problem is.
Instead of dwelling on the causes, symptoms, and cures of innumeracy, I'm here to equip you with a few straightforward rules of thumb. These rules are designed to be simple and easy to apply, empowering you to take control of your financial decisions.
You can use them to see if your decision-making changes.
For me, these simple equations and rules provided a clear target. They allowed me to gauge my progress and understand how far I needed to go to reach my financial goals. I'm confident they can do the same for you, providing a practical and reliable guide for your financial decisions.
I won’t bombard you today, as the fewer and the simpler, the better.
So, let’s start with five simple rules to see if they change how you think.
The Rule of 72
The Rule of 72 is one you’ve probably heard of. And you might be wondering why I’d even include such a rule. Let me first state the rule, and then we’ll talk about how to use it.
For most people, the Rule of 72 tells them how long it will take to double their money if they invest it at a constant rate of return.
For example, if you earn 10% per year on your portfolio, it will take 72/10 or 7.2 years to double it.
If you wanted to back out the math, assume you had a $100,000 portfolio.
$100,000.00 x (1 + 0.10) ^ 7.2 = $198,622
The Rule of 72 isn’t perfect. But near enough is good enough in this case.
If a superstar financial advisor earns you 20% per year, it’ll only take 3.6 years to double your portfolio.
Now, let’s use this rule to look at inflation… something the USG doesn’t want you to do.
Historically, central banks have tried to keep interest rates around 2%. That meant a currency lost half its purchasing power in 72/2 or 36 years. You’d barely notice the loss in purchasing power, as it’d take so long to rear its ugly head.
You’d probably go to the grocery store and wonder why eggs are “suddenly” double what they used to cost in 1983. We’ve all done something like that, haven’t we?
However, with inflation hitting 10% as it had a year or two ago, a currency loses half its value in only 72/10 or 7.2 years.
Realistically speaking, let’s say Chairman Pow comes out and says, “We’d love rates to go back down to 2%, but that’s just not realistic. We’re now happy with a 4% target.”
In that case, the dollar would lose half its purchasing power in 72/4 or 18 years. If you think eggs are expensive now, just wait until 2044!
The Rule of 72 is a great way to examine returns and purchasing power erosion.
Net Worth Indicator
This is a great targeting mechanism, and I regrettably only just found it. It’s from The Millionaire Next Door by Thomas J. Stanley and William D. Danko.
Multiply your age times your realized pretax annual household income from all sources except inheritances. Divide by ten. This, less any inherited wealth, is what your net worth should be.
If you hit this number, you’re an AAW or average accumulator of wealth.
According to the authors, to be considered a PAW, or prodigious accumulator of wealth, you “should” have at least twice this number.
What I like about this indicator is that it’s simple to calculate and gives you a target.
Full disclosure: I’m a UAW, which means I’m an under-accumulator of wealth.
But I won’t use this number to feel bad. I choose to think bigger and get better results.
If you’re unhappy with what this number tells you, I suggest you do the same.
Julian H. wrote in with this great question about the formula:
I'm familiar with The Millionaire Next Door book and have always wondered what the logic behind the formula age x income / 10 is. Do you have any knowledge about that? There are no specifications in the book, and I can't find anything valuable on the Internet.
Thanks in advance.
Best.
Julian H.
Julian, as far as I can see, this formula is produced with linear regression. The authors took net worth, age, and income and produced a line of best fit.
The 50-30-20 Rule Tweaked
The 50-30-20 Rule is a popular budgeting strategy that can help you manage your monthly paycheck effectively. It suggests allocating your income into three categories: needs, debt repayment, and future investment.
It’s super simple:
- 50% of your income goes to paying your “needs.” These include rent or mortgage payments, car payments, groceries, insurance, health care, minimum debt payments, and utilities.
- 30% of your income goes to paying down your debt. Once that’s done, these become discretionary entertainment expenses.*
- 20% of your income goes to future investment.
*In the original formulation, 30% go to your “wants.” That’s fine, but paying down your debt to zero takes priority.
I couldn’t believe how fast my debt disappeared. It took about six to twelve months, but it was gone—and gone for good.
I’ve only run a monthly credit card balance once or twice in the last twenty years, and it’s thanks to this little system.
3x Rule for Buying a House
Another one I love, and that would keep many rich people out of trouble, let alone those of lesser means.
Never spend more than three times your gross annual income on a house.
I bought the house I currently live in using this rule.
My down payment was ready and didn’t empty my account, and my monthly payments are easily manageable.
Far too many people only calculate what their monthly payments would be at the current rate of their mortgage. But if you’ve got an adjustable-rate mortgage, that could quickly end in tears.
There’s no need to overpay for a McMansion.
The Normal Distribution (Bell Curve)
Finally, we get to simple probabilities.
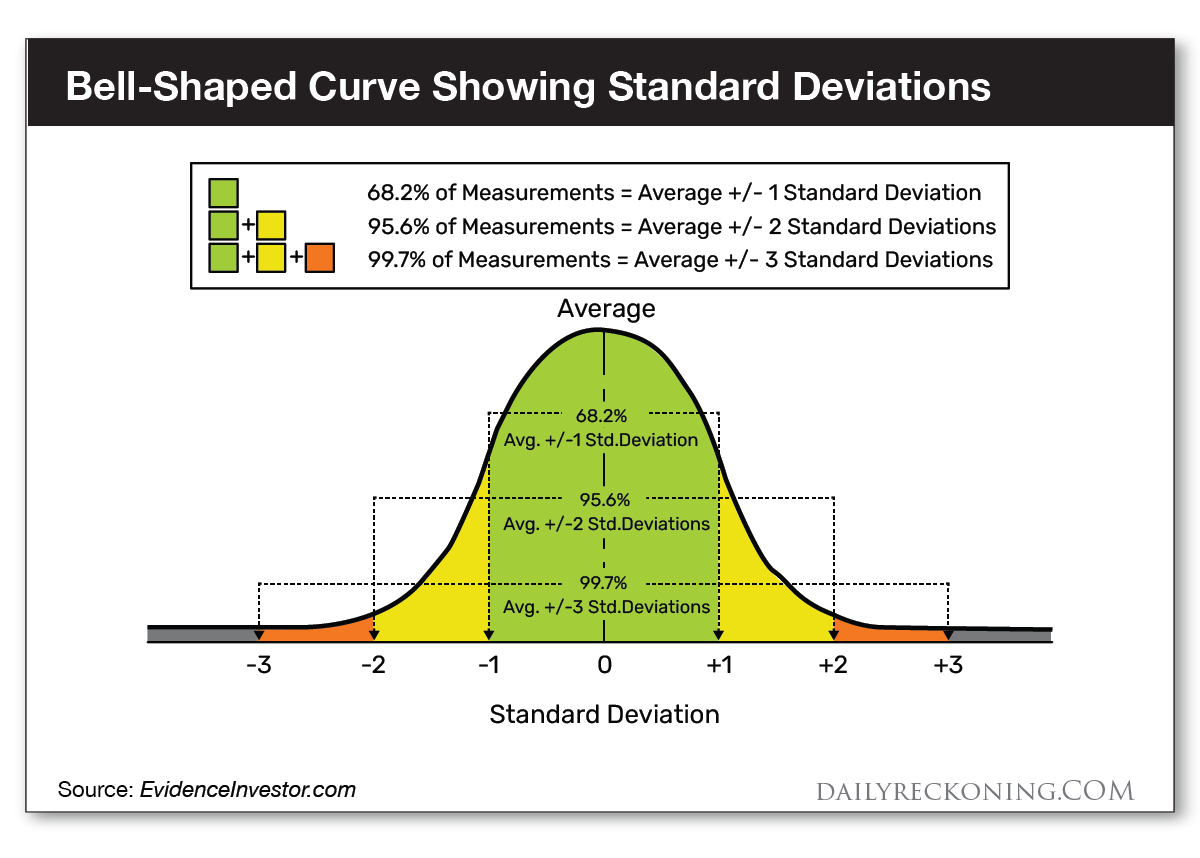
Again, this is just a rule of thumb. Nothing in finance is “normal.”
But this can help you distinguish investing realism from fantasy.
Let’s give an example.
Let’s say Stock ABC has earned, on average, 5% per year. But that return is accomplished with a standard deviation around that 5% average of 2%.
If we assume normal returns – a dangerous thing in finance, but we do it all the time – then ABC has a 68% chance of returning between 3% and 7%.
It has a 95.6% chance of returning between 1% and 9%.
And it has a 99.7% chance of returning between -1% and 11%.
Here’s the thing, though: it certainly can crash far below a -1% return. It may moonshot 45% of the FDA's approval of its new drug, especially if my friend and colleague Ray Blanco put it on his list!
But the probability of either of those scenarios happening is very low.
Knowing this distribution is essential for setting investor expectations and gauging the market's opinion of a potential investment.
If you can adjust your thinking to being more probabilistic, you’ll be shocked at how different the world looks.
Wrap Up
The absolute last thing I wanted to do was to patronize you.
But I also don’t want to assume you know things you may not know.
So I hope that, at the very worst, this was just a refresher on things you may have put on the back burner.
But if there is a lot of new material here, I can’t encourage you enough to deploy this new knowledge as early and as often as possible.
If you’d like to see more of this, please let me know here. And if you found this the least bit unhelpful, do let me know that as well.
I’ll see you on Monday when it’s back to regularly scheduled programming!
The Lost Round Trip
Posted September 25, 2026
By Sean Ring

The Hunt for Red November
Posted September 24, 2026
By Sean Ring
The Straits Strangle
Posted September 23, 2026
By Sean Ring
The Price Behind the Price
Posted September 22, 2026
By Jim Rickards

Baptists, Bootleggers, and Bots
Posted September 21, 2026
By Sean Ring