Posted July 18, 2024
By Sean Ring
Training Shiny Young Things
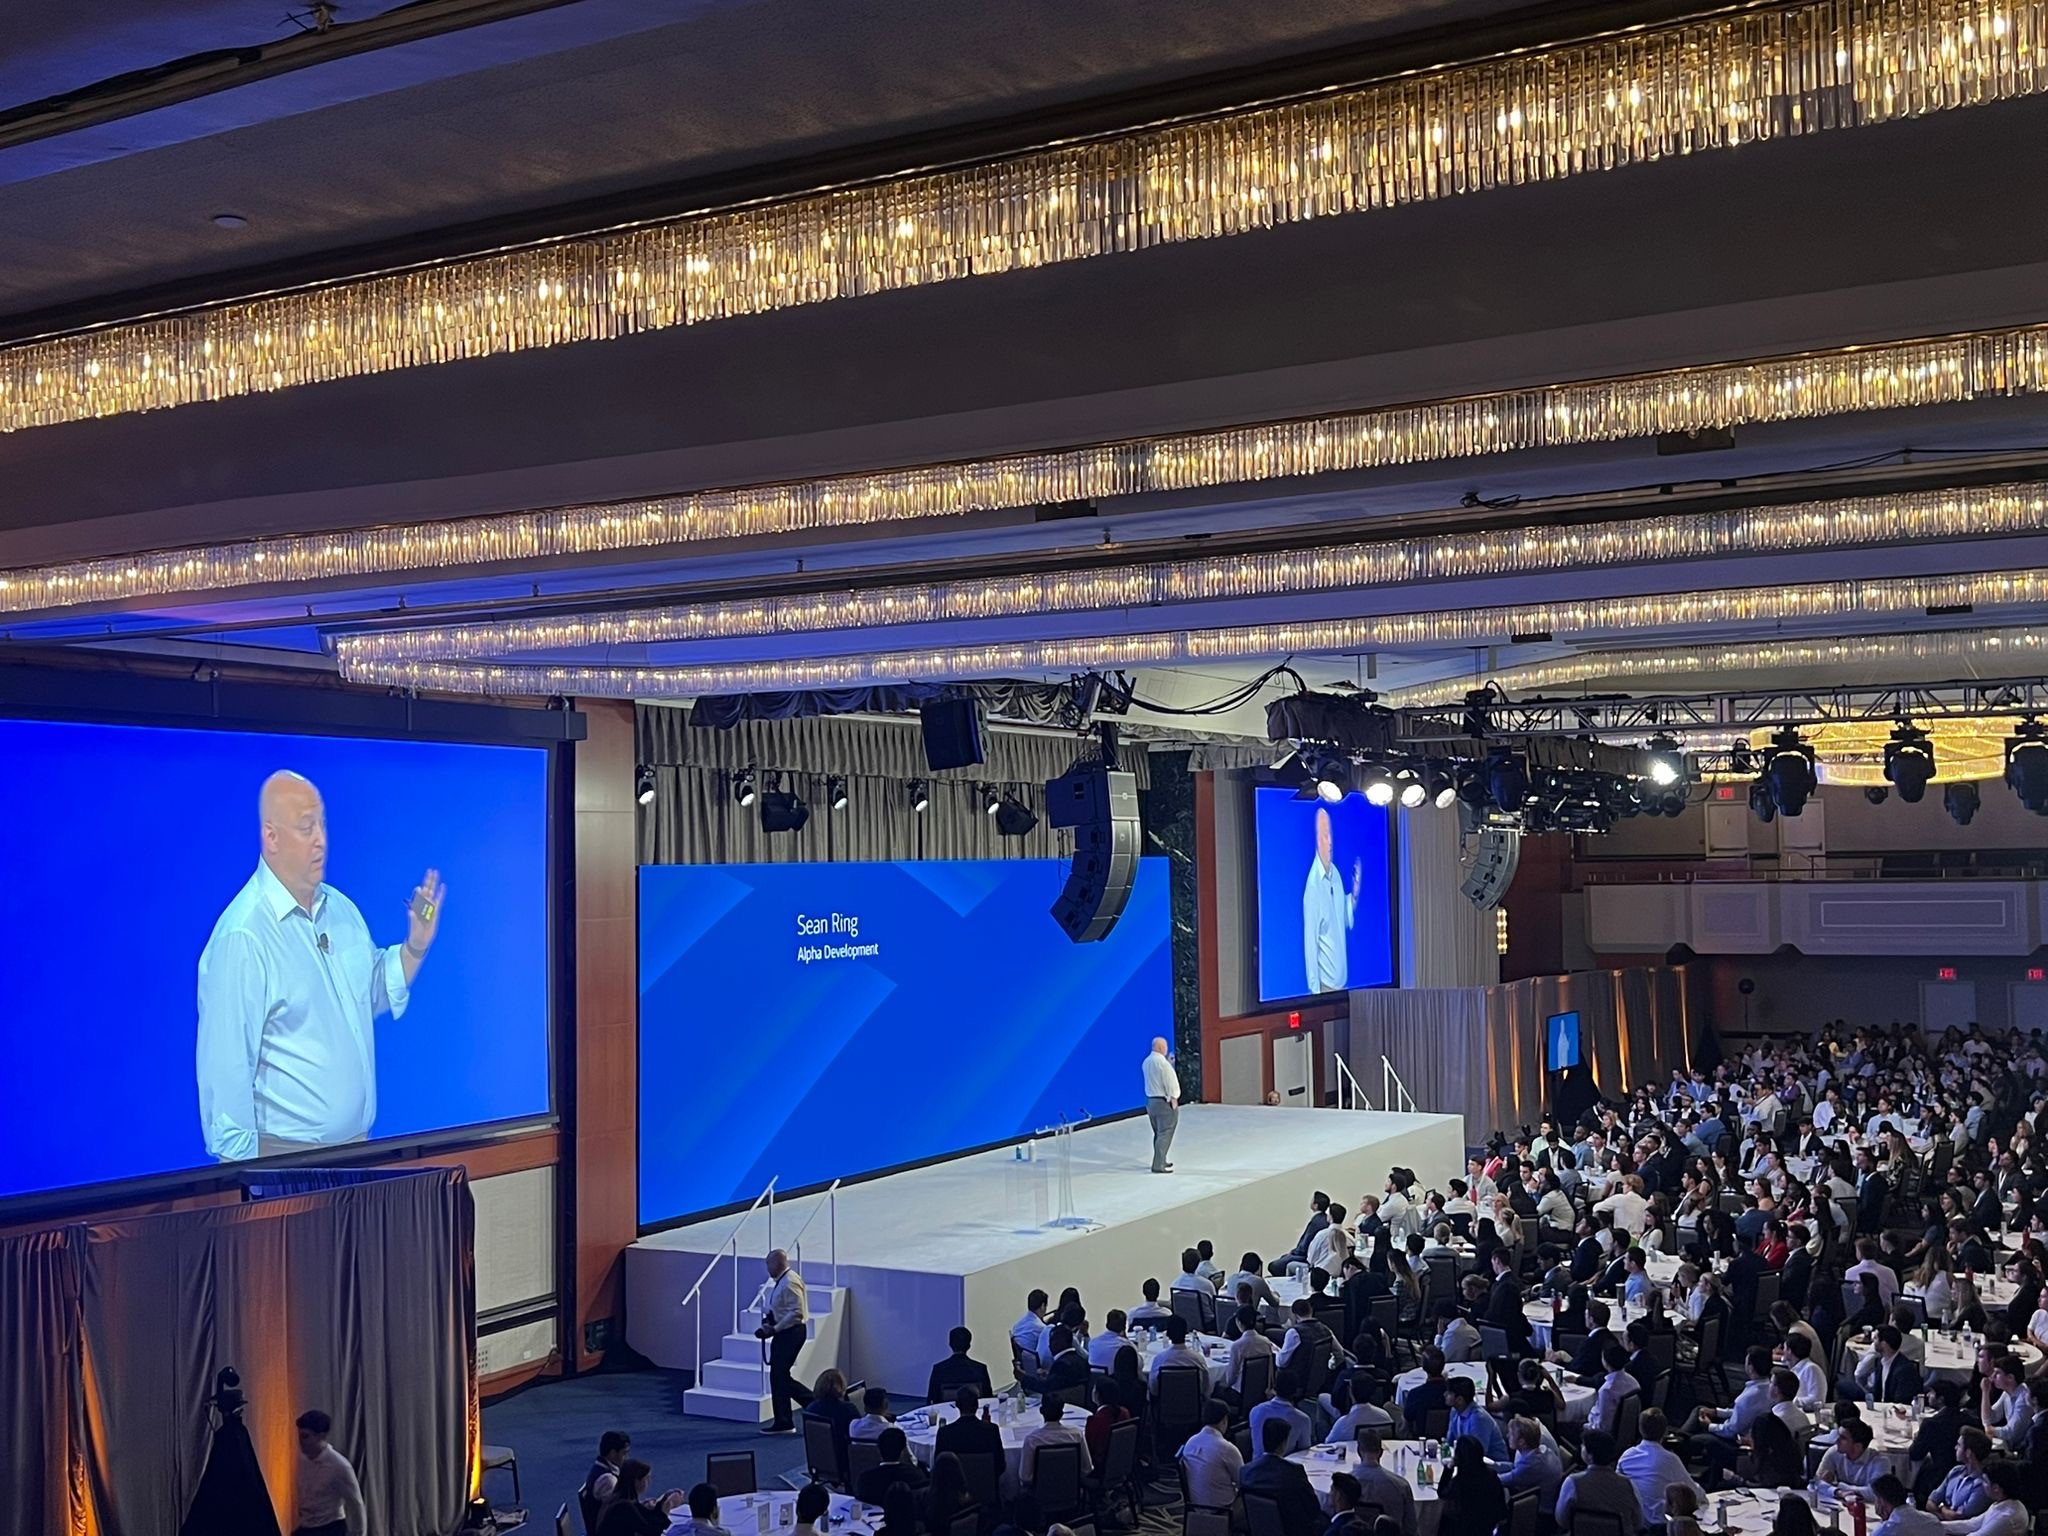
Yours truly speaking to 1,600 new hires at a big bank’s graduate training.
While writing the Rude is the most incredible job in the world, to shake things up every summer, I teach banking graduates.
What are banking graduates, you ask?
So, who exactly are these “banking graduates?” They’re the fresh-faced, eager minds who have just stepped out of university or business school and landed a job at a bank. Every bank conducts its own training, but since the senior staff are already tied up with their own responsibilities, they call on experts like me to show these graduates the ropes.
Our mission, as trainers, is to equip these graduates with the necessary skills and knowledge to be 'desk ready '. This banking jargon essentially means they'll be at a level of competence that won’t leave their colleagues regretting the decision to hire them.
I love that job, too. If you’ve been reading the Rude for any fraction of time, you’ll know that no one loves the sound of my voice more than I do. When writing the Rude, I hear my subvocalized thoughts as I type. But when I’m teaching, I get to shout to the rooftops.
While I’m here, I thought I’d take you through what I do and how I do it during the summers.
First Things First
You must know I partied through Villanova and had no chance of going through one of these fancy programs myself. Only a few of my college professors were worth listening to; the rest were garbage. I felt the same way about London Business School. I thought my education hurt my career. So when I left my broking job in London, I felt passionate about teaching finance and economics in an exciting and easily digestible way.
When I started in March 2007, my teaching colleagues were excellent at their jobs and generous about sharing how they made their classes enjoyable. My firm at the time, 7city Learning, practically ran all the graduate training for the big banks in New York and London, along with CFA training and preparation for the British equivalent of the Series 7 examinations.
I got more of an education after I left banking than when I was in the business! And funnily enough, I feel I’ve taken another leap forward working with Jim, Byron, Dan, Zach, Ray, and the rest of my most excellent Paradigm Press colleagues.
How do we go about teaching all this stuff?
The Course(s)
I remember when I got my offer letter from Lehman Brothers in 1997. I was thrilled. My mother told me how proud she was. And then she asked this question: How do banks make all that money? I had no idea. So, the first thing we cover is banking: how it works, why it’s so important, and how banks profit from their clients.
We’d be in a bank for three to six weeks in a perfect world. But that’s not reality anymore. But for old time’s sake, let me show you an ideal couple of weeks.
After the first day covering banking, we’d move into what I call Trader Macroeconomics. We talk about mathematical economics, so they know what that is. However, it’s mainly focused on the numbers the Bureau of Labor Statistics and other organizations release throughout the month. GDP, inflation, and unemployment are heavily covered, for example.
Next, we’d have a day on foreign exchange. Currencies are a pain to understand, so you need a full day. What mainly moves currencies is the macroeconomic outlook of the country where the currency is from and the interest rate differentials between the home currency and the foreign currency.
After that come bonds, as interest rates would’ve been introduced in foreign exchange. Since this is the market's largest segment, it needs its own day.
For the final day of the week, it’s equities, which is what most of the kids were waiting for, anyway.
The following week, we’d kick off with a day of accounting, mainly learning about the big three financial statements. Then, we’d do derivatives over the next two days. On Thursday, we’d do the lifecycle of a client. That deals with how a client evolves through time. Finally, we’d end the course with the lifecycle of a trade, which goes through the operational aspects of trading and clearing.
We offer financial and soft skills training. This entails learning to talk to clients, write emails, and build spreadsheets and presentations.
Then, the kids would break off into specialist groups, such as investment banking, sales and trading, operations, or private banking.
Private Banking
I used to train the markets division much more, but they shrunk, thanks to algorithmic trading. Algorithmic trading is when machines buy and sell instead of humans.
Because of my experience working with private bankers in Hong Kong, I've mainly taught the private banking curriculum for the past few years.
What are the essential parts of that curriculum? Let me explain.
Asset protection
This answers the question, “How do I protect what I’ve already earned, saved, and invested?”
Trusts, foundations, and companies are used as asset wrappers to protect and manage assets. Each structure has its unique features and benefits. Here's an overview of how they can be used:
1. Trusts:
A trust is a legal arrangement where a person or entity (the trustee) holds and manages assets to benefit another person or group of people (the beneficiaries). Trusts provide a high level of control, flexibility, and privacy.
Here's how they work:
- The settlor: The person who creates the trust and transfers assets into it.
- Trustee: The person or entity responsible for managing the trust assets and ensuring they are used for the beneficiaries’ benefit.
- Beneficiaries: Individuals or groups who will receive the benefits or assets from the trust.
Benefits of using trusts:
- Asset protection: Trusts can shield assets from creditors or legal claims, as the trust, not the individual, legally owns the assets.
- Estate planning: Trusts allow for the efficient transfer of assets upon the settlor's death, potentially minimizing estate taxes and avoiding probate.
- Privacy: Trusts provide confidentiality, as they aren’t publicly disclosed.
- Control: Trust documents specify how the assets should be managed and distributed, giving the settlor control over them even after they are transferred.
2. Foundations:
Foundations are legal entities established for charitable, philanthropic, or social purposes. They are
typically funded by a donation or endowment and operated for the benefit of a specific cause or group.
Here's how foundations are used as asset wrappers:
- Founder: This person or entity establishes the foundation and provides the initial endowment.
- Board of Directors: Individuals responsible for managing the foundation's activities and ensuring compliance with its mission.
- Beneficiaries: The recipients of the foundation's charitable activities or support.
Benefits of using foundations:
- Philanthropy: Foundations provide a structured approach to supporting charitable causes and positively impacting society.
- Asset protection: Assets transferred to a foundation are legally separate from the founder's assets, protecting them from personal liabilities.
- Tax benefits: Depending on the jurisdiction, foundations may enjoy tax advantages, such as exemptions or deductions for charitable donations.
3. Companies:
Companies, also known as corporations or business entities, are widely used for commercial purposes.
While their primary function is not typically asset protection, they can be utilized as asset wrappers in certain situations.
Here's how companies can be used:
- Shareholders: Individuals or entities who own shares in the company, representing their ownership interest.
- Directors: Individuals responsible for managing the company's affairs and making operational decisions.
- Officers: Executives appointed to oversee specific functions within the company, such as CEO, CFO, etc.
Benefits of using companies:
- Limited liability: A company's shareholders generally have limited liability, meaning their personal assets are separate from the company's liabilities.
- Business operations: Companies can be used to conduct business activities, generate income, and accumulate assets.
- Investment management: Companies can hold and manage investments on behalf of their shareholders, providing a layer of separation between the individual and the assets.
It's important to note that the specific rules and regulations governing trusts, foundations, and companies can vary significantly between jurisdictions.
Always consult with legal and financial professionals familiar with the laws in your jurisdiction to determine the most appropriate asset wrapper for your needs.
Portfolio management
This answers the question, “Where do I put all my money?”
Portfolio management in private banking refers to the professional management of investment portfolios for high-net-worth individuals (HNWIs) and ultra-high-net-worth individuals (UHNWIs).
Private banks offer specialized services to clients with substantial financial resources, aiming to preserve and grow their wealth over time.
You can do the same without the bells and whistles.
Here's a quick overview of portfolio management:
-
Client Assessment
-
Investment Strategy
-
Investment Selection
-
Ongoing Monitoring and Reporting
The key here is to put your wealth in investments that don’t keep you up at night.
Minimizing tax liability
This answers the question, “How do I keep my wealth in my children’s hands and not the government’s?”
Minimizing tax liability involves employing legitimate strategies and taking advantage of available deductions, exemptions, credits, and incentives to reduce the overall tax burden.
Here are some general approaches to minimizing tax liability:
-
Optimize Deductions and Credits
-
Maximize Retirement Contributions
-
Consider Tax-Advantaged Investments
-
Timing of Income and Expenses
-
Capital Gains and Losses
-
Tax-efficient Asset Allocation
-
Consider Tax Treaties and International Tax Planning:
-
Charitable Giving (see below)
Why give your money to the government, which redistributes it to complete strangers, when you can ensure your children’s futures?
Estate planning
This answers the question, “How do I know things will be ok after I shuffle off my mortal coil?”
Succession planning involves creating a comprehensive strategy to address the transition of both financial and non-financial assets.
Here are key steps and considerations involved in succession planning:
-
Define Objectives and Goals
-
Identify Successors and Roles
-
Estate Planning and Wealth Transfer
-
Business Succession Planning
-
Family Governance and Communication
-
Philanthropic Planning
-
Tax Planning and Professional Advice
-
Periodic Review and Updating
The trick here is to make sure the smart kids get the company to run. The slow ones will still get the dividends to reap, but keep them away from the machine.
Philanthropy
When a high-net-worth individual (HNWI) or ultra-high-net-worth individual (UHNWI) engages in philanthropy, several key considerations should be considered to ensure effective and impactful charitable giving.
Here are the primary considerations:
-
Mission and Values
-
Impact and Outcomes
-
Strategic Approach
-
Due Diligence
-
Sustainability and Scalability
-
Engaging Stakeholders
-
Collaboration and Partnerships
-
Measurement and Evaluation
-
Professional Expertise
-
Ethical Considerations
One of my buddies loves elephants. He donates pallets of cash to elephant charities.
To each his own.
Wrap Up
I hope you enjoyed the little trip around what I do over the summers. It should give you a clue about what you need to do, in case you missed anything.
The Yuan Trap
Posted November 06, 2026
By Sean Ring

The 16,000 Who Rule America
Posted November 05, 2026
By Sean Ring
The 87% Solution
Posted November 04, 2026
By Sean Ring

Warsaw Unpacked
Posted November 03, 2026
By Sean Ring
A Crude Tax
Posted November 02, 2026
By Sean Ring
