Posted June 30, 2026
By Sean Ring
The Inequality Tax
You've been told the middle class is squeezed by taxes.
That's not quite right. And the truth is more interesting.
The federal government actually taxes the American middle class less than it did in 1979. The Economic Policy Institute ran the numbers. In 1979, the average federal tax rate on the middle 60% of households was around 18.9%. By 2011, it had fallen to 12.3%. CBO data through 2021 confirms the trend hasn't reversed.
You're paying less to Washington than your parents did.
So why does it feel like you're getting crushed?
Because you are… just not by the villains at the IRS.
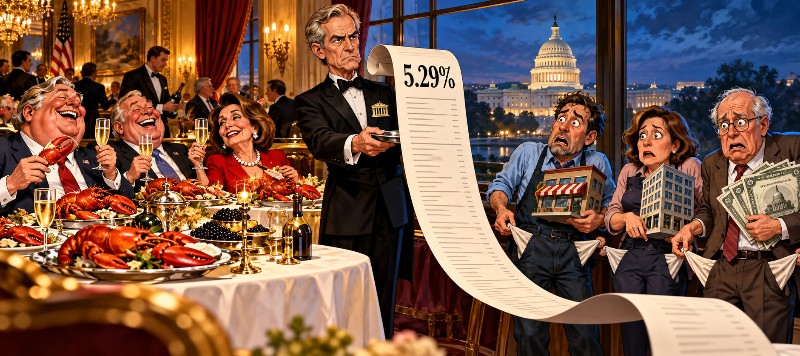
The Inequality Tax
That's what the Economic Policy Institute called it. And it's the most honest label in the whole debate.
Suppose the economy grows 3% every year. In an even distribution, every American would capture 3% higher income on average. But if the gains pile up at the top, it’s a different story. What if the top 1% captures 6%, while the middle captures only 1.5%?
You're not being taxed more. You're just not getting your share of the growth.
EPI put numbers on it. By 2007, the middle 60% would have had incomes roughly 23% higher — about $18,000 more per household — if their income growth had simply kept pace with the overall average. That's a sum of money the middle class never saw. Not because Washington took it, but because the distribution of gains tilted hard toward the top.
That's the Inequality Tax. No bracket. No Form 1040 line. Just an unseen check that never arrived.
The Numbers That Should Shock You
CBO's latest work on household income from 1979 to 2021 tells the full story.
The top 1% roughly doubled their share of after-tax income. In 1979, they held about 7–8% of after-tax income. In recent years, they have held about 13–14%.
The middle 3/5ths saw their share fall.
Pew Research's 2024 report puts it simply. In 2022, upper-income households earned 7.3 times as much as lower-income households. In 1970, that ratio was 6.3.
On wealth, it's starker. The Federal Reserve's distributional data shows the top 1% held 31.7% of all U.S. wealth as of late 2025. The bottom 90% together hold roughly the same amount as the top 1% alone. In other words, the top 10% holds about 70% of the country’s wealth, while the rest split the remaining 30%.
America's middle class is no longer the owner class.
The European Twist
Here's where most people have it backward.
Progressives hold up European welfare states as the model. More benefits. Better safety nets. A fairer deal for ordinary people.
They're right about the benefits. They're wrong about who pays for them.
The American Action Forum pulled together OECD data and found a striking fact. In the U.S., the top 10% pay over 45% of income and payroll taxes. In France, the top 10% pay less than 30% of the total tax take. The European average for the top decile is just under 35%.
So Europe taxes the rich less than America does. Much less.
Who makes up the difference?
The middle class. French and German middle-class workers pay around 50% of the total tax burden. Italy is at 47%. Sweden at 43%. Spain at 40%.
The American middle class pays just under 30%.
Europe's welfare state is a middle-class-funded enterprise. It is built on the backs of working people who face combined tax rates close to 50% in France and Germany, versus around 30% in the U.S.
That's a much worse deal. No wonder all those European football fans are loving their TGI Fridays right now!
The Hidden Welfare State for the Wealthy
There's one more layer that Austrian economists and students of Bastiat will recognize immediately.
The U.S. doesn't just have a public welfare state. It has a private one, delivered through the tax code, that tilts hard toward the top.
Pension tax subsidies — 401(k)s and IRAs — are worth over $13,000 per year to households in the top 1%. They're worth about $1,000 to middle-class families. The deduction is worth more when you're in a higher bracket. So the people least likely to need the help get the most of it.
The mortgage interest deduction, the employer-provided health insurance exclusion, and 529 college savings plans — all of these provide larger benefits to high-income households who itemize.
Editor’s Note: I always recommend hiring an accountant to do your tax returns. The layman can’t keep up with all the tax code changes every year.
Government spending “grows” the national GDP. But tax subsidies create invisible transfers that don't show up the same way. Neither of them produces prosperity. Goodhart's Law cuts both ways: the measures are being gamed.
Wrap Up
Yes, your suspicion that the system is rigged is vindicated. But it’s not by the income tax brackets on paper, but by who captures the economic gains. After decades of FOMC-engineered asset-price inflation, the top owns roughly 40% of all financial wealth. The starter homes, the stock portfolios, and the compounding returns went to people who were near the spigot.
Second, don't let anyone sell you a Nordic model without showing you the price tag. High-benefit welfare states require high taxes on everyone, especially workers. There’s no such thing as taxing only the rich to pay for everything. The math doesn't work. The moment welfare spending hits 23% of GDP, as in many European nations versus 16% in the U.S., the bill gets spread wide.
Third, the practical move. In an era of Cantillon-Effect wealth distribution, you have to think about what your money is doing. Real assets like energy, land, and companies that extract and produce goods have a better claim to gains than paper sitting in a brokerage account.
The income tax isn’t annihilating the American middle class.
It’s being slowly crowded out of the asset-owning economy by decades of bad monetary policy, regulatory capture, and a tax code that looks progressive on the rate schedule and isn't in practice.
The IRS isn't the problem.
The Inequality Tax is.
Just Blew It.
Posted October 08, 2026
By Sean Ring
Fission Accomplished?
Posted October 07, 2026
By Sean Ring

The Lease of Their Worries
Posted October 06, 2026
By Sean Ring

You Can’t Print a Smelter
Posted October 05, 2026
By Sean Ring

Pardon My Financial French
Posted October 02, 2026
By Sean Ring