Posted October 20, 2026
By Zach Scheidt
A COLA, But No Smile
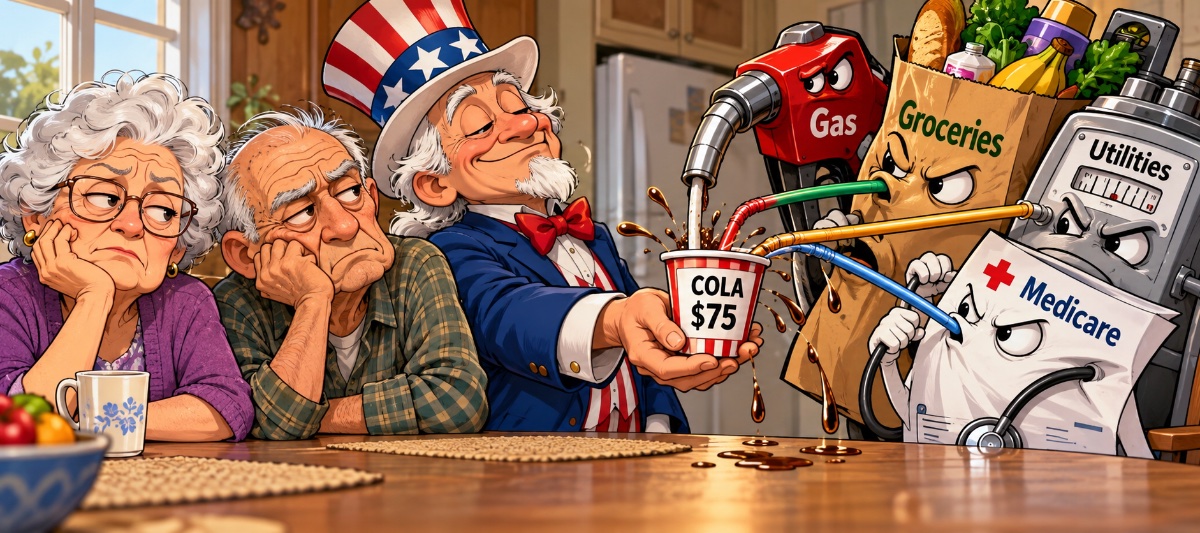
Editor’s Note: The Swamp Things have finally found a way to give you a raise without making you any richer. Social Security checks will rise by about $75 a month next year. Don’t spend it all at one gas station! Today, my old friend Zach Scheidt returns to the Rude with a way to get ahead of the DC parlor game.
Hi, Zach here…
This week, the Social Security Administration announced that retirement checks will increase by 3.6% in 2027.
That's the biggest raise since 2023. And for the average retired worker, the monthly check goes from about $2,095 to $2,170 starting in January. That's roughly $75 more each month, or about $900 for the year.
Of course, an extra $75 each month is nice. But if you’re a retiree facing stubbornly high inflation, that $75 might feel more like a hollow gesture than a truly helpful raise.
So this week’s announcement won’t relieve the pressure you've been feeling. And there's an even bigger problem on the horizon that this raise doesn't fix at all.
The Inflation You Actually Feel
The same morning Social Security announced its raise, the government released its latest inflation report.
According to the Bureau of Labor Statistics, prices rose 3.7% over the past year. So before your first bigger check even arrives, the raise is already behind.
And that 3.7 percent is the flattering number.
Look at what's driving inflation in today’s economy:
- Energy prices are up 20.4% from a year ago.
- Gasoline is up 34.2%.
- Heating oil is up a staggering 74%.
- Electricity is up 4.4%.
Now, you'll hear the experts on TV talk about "core" inflation, which came in at a much calmer 2.6%. Core inflation strips out food and energy. The reasoning is that those prices are "volatile," so they muddy the picture.
Well, who cares if they're volatile? You still have to pay them!
You still drive to the grocery store, to the doctor, and to see the grandkids. You still have to heat your home this winter. Nobody at the gas pump gives you a discount because the price is volatile.
Food is the same story. Grocery prices have cooled a bit this year. But that's cold comfort when your cart costs roughly 30% more than it did in early 2020. Those higher prices didn't go away. They just stopped climbing as fast.
Here's what really matters for retirees. Your budget probably doesn't look like the "average" household the government measures.
A bigger share of your money goes to the necessities: housing, utilities, gasoline, groceries, and health care. Fewer of your dollars go to new cars, gadgets, and the other things that have been getting cheaper. (New car prices are up just 0.6% this year. Used cars are actually down.)
Those cheaper categories pull the official average down. But they don't help you much if you're not shopping for a car. So your cost-of-living adjustment pays you back for an inflation rate that's lower than the one you're actually living with.
And Medicare takes its bite, too. The standard Part B premium is projected to rise to $209.50 a month. That’s not much for seniors who spend a large portion of their income on medical costs.
This isn't a one-year problem, either. According to The Senior Citizens League, Social Security benefits have lost about 20% of their buying power since 2010.
Year after year, the raises have fallen short of what retirees actually spend.
Meanwhile, the Clock Is Ticking
An even bigger issue is looming on the horizon.
Social Security's own trustees project that the trust fund that pays retirement benefits will run dry in late 2032. That's about six years from now.
When that happens, incoming payroll taxes will only cover about 78% of scheduled benefits. Unless Congress acts, that's an automatic cut of roughly 22%.
A bigger raise this year doesn't fix that. Bigger checks just mean the money goes out the door faster.
I expect Congress will patch this up eventually. They usually do, at the last minute. But do you really want your retirement to depend on what Washington decides in 2032? I sure don't.
Build Your Own Raise With a Barbell
You can't control the COLA, and you can't control Congress. But you can control your own investment portfolio. My favorite way to do that is with a barbell strategy.
Picture a barbell. Heavy weight on one end, lighter weight on the other, and nothing in the mushy middle.
The heavy end: reliable income (70% to 90%)
I recommend keeping most of your money in a strategy that produces reliable income.
Think of it as your own paycheck, and you're the one in charge of it. If you don't need the income right now, reinvest it. That's how your income stream compounds into a bigger one over time.
One of my favorite income strategies is selling cash-secured puts. Here's how it works in plain English.
You find a quality stock you'd be happy to own, and you agree to buy it at a lower price than where it trades today. Another investor pays you cash up front for that promise.
Say a stock you like trades at $50. You agree to buy 100 shares at $45 any time over the next six weeks, and you're paid $1 per share, or $100, today. You set aside $4,500 in cash in case you need to buy.
If the stock stays above $45, you keep the $100 and can do it again. If it drops below $45, you buy a stock you wanted anyway at a discount, and you still keep the $100. (This is a simplified example, not a recommendation.)
Done patiently and consistently, a strategy like this can help grow your income faster than inflation.
But it takes discipline: Stick to quality companies. Only sell puts on stocks you'd truly be happy to own. And don't chase the fattest payments, because those usually come with the most risk.
The light end: swing for the fences (10% to 30%)
The rest of your money can go into a much more aggressive strategy. This is where you go after trades with big upside.
Not every trade will work, and that's okay. That's exactly why this end of the barbell is small. A loss here won't sink your retirement.
But here's the key move. When you book a big win, take some of the profits off the table and move them into your income basket. Every win permanently raises the income you collect month after month. That's how the two ends of the barbell work together.
You Don't Have to Do This Alone
Here's the good news. Paradigm has experts on both ends of this barbell. Our trading services are built to target big gains. And seasoned income investors know how to generate reliable income month in and month out.
Social Security just gave you a $75 raise. Let's work on giving you a real one.
Be the House
Posted November 09, 2026
By Sean Ring
The Yuan Trap
Posted November 06, 2026
By Sean Ring

The 16,000 Who Rule America
Posted November 05, 2026
By Sean Ring
The 87% Solution
Posted November 04, 2026
By Sean Ring

Warsaw Unpacked
Posted November 03, 2026
By Sean Ring